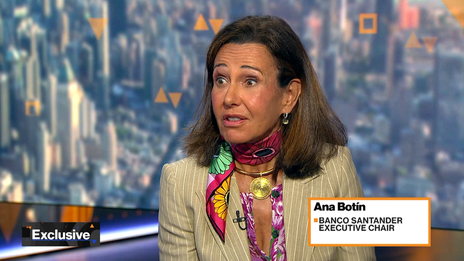
Santander shares are down 0.5% at EUR11.7 in Madrid after Jefferies downgraded the stock from "Buy" to "Hold", while raising TP from EUR12 to EUR13, as part of a broader research note on Spanish banks.
According to the US broker, Spanish banks are entering the Q3 earnings season amid a rise in the cost of equity linked to recent market volatility, although their fundamentals remain solid.
"Volume growth remains a key strength, while the persistence of high interest rates in the European Union should continue to support net interest income over the medium term. Inflation could put some pressure on costs in 2027, but asset quality remains robust," it added.
Following the recent decline in equity valuations, Jefferies believes the sector still offers attractive investment opportunities. It therefore upgraded Bankinter shares from "Hold" to "Buy", increasing its target price for them from €17 to €18.
Jefferies prefers Bankinter to Santander
The broker notes that, following its underperformance since the beginning of the year, Bankinter now trades at a discount to CaixaBank and Unicaja on a one-year forward P/E basis, whereas the stock has historically traded at valuation premiums of around 15% and 25%, respectively.
"We believe this discount is unjustified, particularly given the greater sensitivity of Bankinter's net interest income to a high-interest-rate environment in the short term," it said, while also raising its EPS forecasts for the group by 3%.
Conversely, Jefferies downgraded Santander from "Buy" to "Hold", with EPS estimates for 2027 and 2028 slightly below consensus, by a few percentage points (low single digits).
"While the bank is undergoing a major transformation and showing strong earnings momentum, with estimated average annual EPS growth of 17% between 2025 and 2028, we believe these prospects are already reflected in consensus forecasts," the broker explained.
Banco Santander, S.A. is Spain's largest banking group. The activity is organized into three sectors:
- commercial banking: retail banking activities and specialized financial services (consumer loans, mortgages, etc.);
- investment, financial and market banking: classic and specialized financing (financing acquisitions, projects, etc.), financial engineering (consulting on mergers and acquisitions, stock transactions, etc.), intervention in the stock, rate and exchange markets, etc.;
- asset management and private banking. The group also develops bank insurance activities through Santander Seguros and Banesto Seguros.
At the end of 2024, the group managed EUR 1,095.8 billion in current deposits and EUR 1,076.3 billion in current credits.
The products and services are marketed via a network of 7,124 branches worldwide.
This super rating is the result of a weighted average of the rankings based on the following ratings: Valuation (Composite), EPS Revisions (4 months), and Visibility (Composite). We recommend that you carefully review the associated descriptions.
Investor
Investor
This super composite rating is the result of a weighted average of the rankings based on the following ratings: Fundamentals (Composite), Valuation (Composite), EPS Revisions (1 year), and Visibility (Composite). We recommend that you carefully review the associated descriptions.
-
Global
Global
This composite rating is the result of an average of the rankings based on the following ratings: Fundamentals (Composite), Valuation (Composite), Financial Estimates Revisions (Composite), Consensus (Composite) and Visibility (Composite). The company must be covered by at least 4 of these 5 ratings for the calculation to be carried out. We recommend that you carefully review the associated descriptions.
-
Quality
Quality
This composite rating is the result of an average of rankings based on the following ratings: Returns (Composite), Profitability (Composite) and Quality of Financial Reporting (Composite), and Financial Health (Composite). The company must be covered by at least 2 of these 3 ratings for the calculation to be performed. We recommend that you carefully read the associated descriptions.
ESG MSCI
ESG MSCI
The MSCI ESG score assesses a company’s environmental, social, and governance practices relative to its industry peers. Companies are rated from CCC (laggard) to AAA (leader). This rating helps investors incorporate sustainability risks and opportunities into their investment decisions.